Buyers can pay different prices for the same goods. One buys a small batch at the list price, another gets a discount for a large order, and a third is offered the remaining stock from a previous series. When customs finds a more expensive shipment, the question is whether the duty must now be calculated using someone else’s price.
Customs value is determined first of all on the basis of your own transaction. This is called method 1, the transaction value method. The calculation includes the price paid or payable for the goods when sold for export to the Eurasian Economic Union (EAEU), together with the additions required by the Code, such as delivery costs to the specified place of arrival. The conditions for this calculation are set out in Articles 39 and 40 of the EAEU Customs Code.
A more expensive purchase by another importer may raise questions for customs. But a price difference alone does not establish that the customs value of your shipment is inaccurate. The terms of the other shipment and the arrangements with your own seller also matter.
For example, a catalogue price may relate to a different configuration or a small order. The price of an earlier shipment may already have included expensive air freight. Even the unit of measure can differ: a price per item and a price per package can look like two comparable figures until the goods description is read. The model, manufacturer, quantity, import period, delivery and terms of sale show whether the selected comparison is suitable at all.
If customs has provided only the amount, you can ask for the terms of the other shipment in your response to its request. Your own price can be explained, for example, by discount letters, an agreed order and proof of payment. These can be submitted without waiting for details of the other purchase.
The terms “identical” and “similar” have a specific meaning in Article 37 of the EAEU Customs Code. Identical goods are the same in all respects, although minor differences in appearance are permitted. Similar goods may differ, but they must have similar characteristics, consist of similar components made from the same materials. These features must enable them to perform the same functions as the goods being valued and to be commercially interchangeable with them. The assessment also takes into account quality, reputation, trademark, country of production and the rules for selecting information about the manufacturer.
| Identical | The same in all respects; minor differences in appearance are allowed. |
|---|---|
| Similar | Similar characteristics, the same materials and commercial interchangeability. |
Paragraph 10 of Resolution No. 49 of the Plenum of the Supreme Court of the Russian Federation dated 26.11.2019 allows a substantial deviation from the value of comparable transactions involving identical or similar goods to be treated as an indication that the declared value may be inaccurate. Information from customs databases is used first. If there are no suitable transactions there, other official or publicly available sources may be used, including information from manufacturers, official distributors and product price catalogues. But customs disagreement with a lower price, or a difference from domestic market prices, does not replace verification of the transaction.
The order and specification show what goods the buyer purchased, in what quantity and at what price the parties agreed. The invoice - the commercial bill - states the amount payable. The technical description clarifies the configuration. If the same model is designated differently in these documents, the connection between the documents and the same goods should be explained.
In the response to a request, a specific line in the specification can be matched to the technical description, and the invoice amount to the price calculation. Correspondence about the price should relate to the same order. A short note for an attachment can explain what it proves: the model, configuration, quantity or payment terms.
Payments to the seller should be reviewed separately. Paragraph 3 of Article 39 covers payments specifically for the imported goods that the buyer has made or must make directly to the seller or to another person for the seller’s benefit. It is therefore necessary to check whether there are any other payment obligations relating to the same shipment in addition to the invoice. If the parties agreed on deferred payment, the absence of payment on the declaration date does not rule out method 1. The documents must make it possible to establish the amount payable and the payment arrangements.
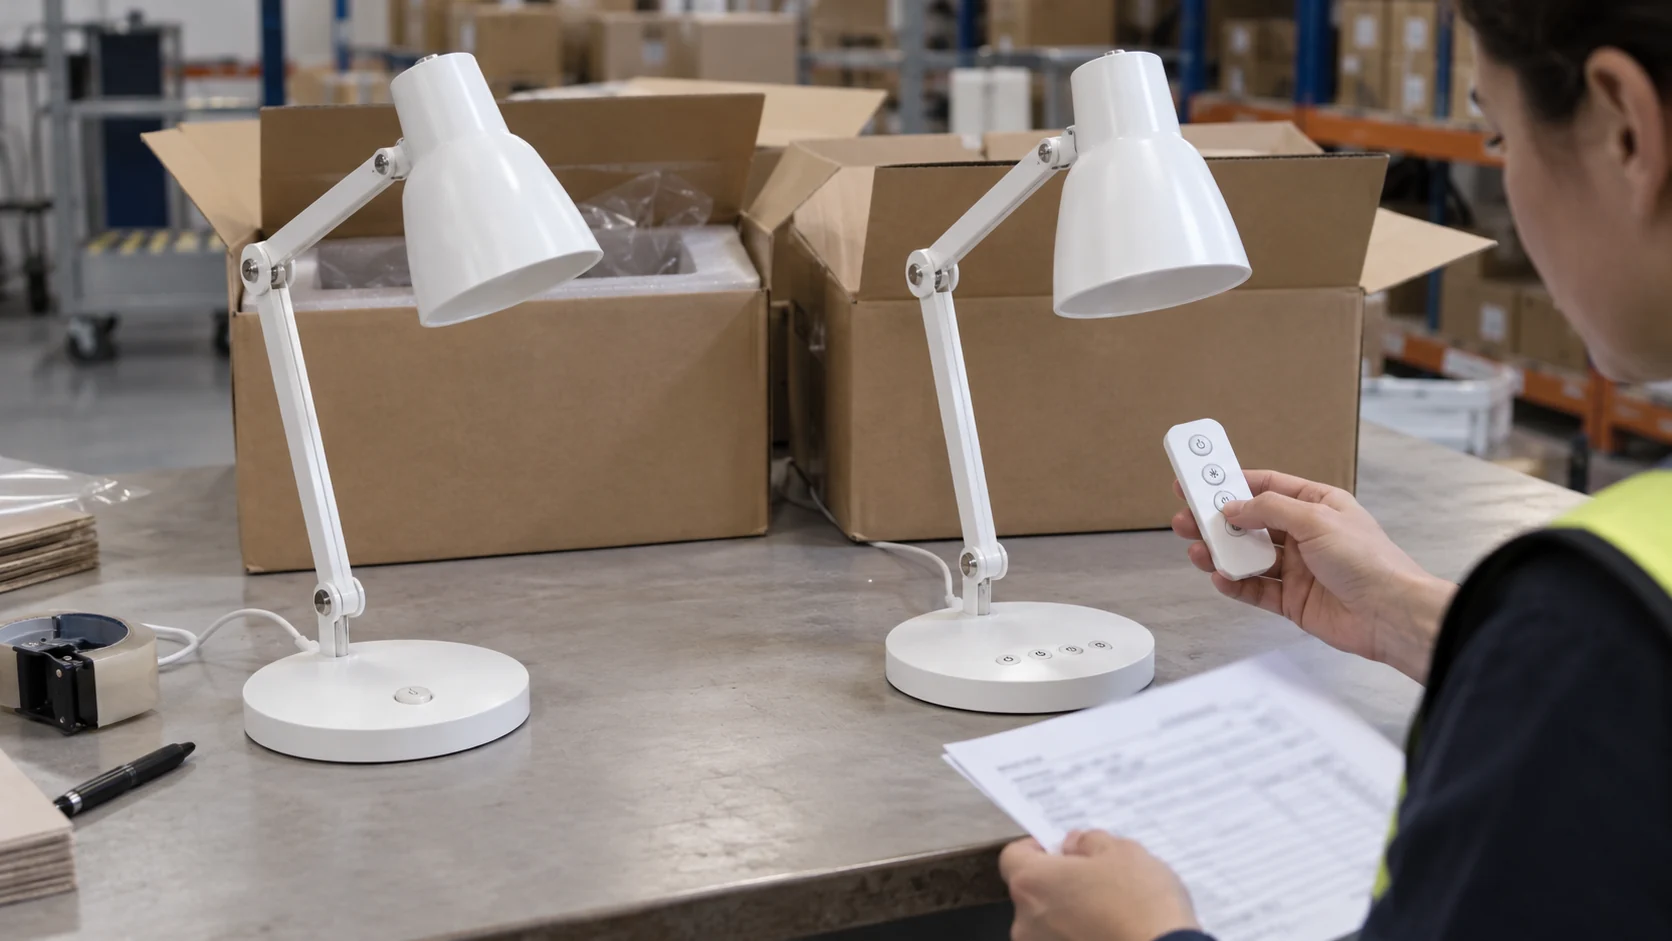
For example, basic-version lighting fixtures are imported. Customs compares them with more expensive fixtures that include a remote-control unit. If that unit is not part of the purchased configuration, the technical description and specification explain a material difference between the goods.
The buyer’s specification identifies the basic version. The technical description confirms that the configuration does not include the control unit. Correspondence before the shipment concerns the same version, and the invoice contains the same designation, quantity and agreed price. The response can show this sequence of documents and explain that the customs comparison concerns goods with different configurations.
If it is necessary to calculate how much this difference is worth, the amount of the adjustment will need supporting evidence. This could be, for example, supplier information on the price of the additional unit or another verifiable calculation. Until such data are available, it is better not to construct the amount of the difference independently. The documents already allow the comparability of the goods to be questioned, while the monetary amount of the difference must be supported separately.
A requested document may be held by a foreign supplier or may not be prepared as a separate document at all. This can be explained directly to customs. A request sent to the holder of the document and the holder’s response show that an attempt was made to obtain the information. If the supplier has not yet replied, the importer still has the request itself; if the supplier refused, the importer has the refusal.
Some information can be confirmed by materials already available. The configuration can be seen from the technical description and specification, and the price from the offer, order and correspondence. Whether these documents are sufficient depends on what fact customs is checking: explaining a discount and confirming additional expenses require different information.
Paragraph 9 of Resolution No. 49 links documentary confirmation of customs value to whether the transaction itself can be established, the price information can be matched to the quantity of goods, and the delivery and payment terms can be understood. A separate formal defect in a document that does not disprove that the transaction was concluded on specific terms does not by itself mean that the value is unsupported. Paragraph 8 of the same Resolution instructs courts to proceed from a presumption that the information submitted by the declarant is accurate until customs rebuts it. The declarant is the person who declares the goods or on whose behalf the goods are declared.
Even if the customs comparison turns out to be unsuitable, the other conditions of Article 39 still need to be checked. The contract may contain restrictions on the buyer’s rights to use or dispose of the goods. The Code permits territorial restrictions on resale, restrictions that do not materially affect the value, and restrictions imposed by acts of the Union or by the legislation of the Member States. Other restrictions may affect whether method 1 can be used.
The sale or price must also not depend on conditions or obligations whose effect on the price cannot be determined in monetary terms. Paragraph 19 of Resolution No. 49 requires the specific condition to be identified in such a case. If part of the income or proceeds from a subsequent sale, other disposal or use of the goods is due to the seller, the possibility of the corresponding addition under Article 40 must be checked.
If the seller and buyer are related, that fact alone does not rule out method 1. What matters is whether the relationship affected the price. When the relationship is established and customs identifies indications that the declared value may be inaccurate, paragraph 20 of the Resolution places on the declarant the obligation to confirm that the price was formed without such influence.
If at least one condition in paragraph 1 of Article 39 is not met, method 1 does not apply. But the higher price of the lighting fixture with the additional unit in our example still does not explain why the price of the basic version cannot be used. The technical differences and the purchase terms must be assessed before another shipment’s value is used as the basis for the calculation.
Andrey Bernev, customs lawyer